

Los Angeles Fire Damage Claims Adjuster | Avner Gat, Inc.
If a fire has damaged or destroyed your Los Angeles home or business, your insurance company's first offer is rarely the number you're actually owed. Avner Gat, Inc. has a team of licensed public adjusters who help Los Angeles fire victims recover the full value of their claim, covering structural damage, smoke and soot contamination, lost belongings, and the cost of living elsewhere while your property is rebuilt.
We work exclusively for policyholders. We are never paid by, or affiliated with, any insurance carrier. Our only job is advocating for the settlement you're entitled to under your policy.


Why Los Angeles Fire Victims Need Their Own Advocate
Insurance companies assign their own adjuster to your claim the moment you report a loss. That adjuster's job is to manage the carrier's payout, not to make sure you're made whole. In the aftermath of a major fire, this imbalance becomes even more pronounced: claims volume spikes, contractor and material costs surge, and carriers face enormous financial pressure to control losses across thousands of policyholders at once.
A public adjuster levels the playing field. Avner Gat, Inc. builds your claim around the actual costs to rebuild and replace what was damaged, rather than relying on depreciated or underestimated figures. We handle the negotiations with your insurance company so you can focus on getting your life back to normal.
Public Adjusters vs. Insurance Company Adjusters: What's the Difference?
This distinction is often misunderstood, and it's essential to know before you sign anything from your insurer.
| Aspect | Insurance Company Adjuster | Public Adjuster (Avner Gat, Inc.) |
|---|---|---|
| Who they work for | Employed or contracted by your insurer | Licensed by the State of California to represent policyholders exclusively |
| Primary goal | Control the insurance company's payout costs | Maximize your settlement |
| Financial relationship | Paid by the insurance carrier | No financial relationship with your insurer |
| How they're compensated | Salary or contract fee from the insurer, regardless of your payout | A percentage of your settlement. They only get paid more when you do! |
| Motivation | Often minimizes payouts, even when it isn't in your best interest | Motivated to fight for the maximum amount you're owed |
| Who benefits | The insurance company | You, the policyholder! |
Schedule a Fire Damage Claim Consultation
If a fire has affected your Los Angeles home or business, don't navigate the claims process alone or accept the first number your insurance company offers. Call Avner Gat, Inc. to discuss your claim with an experienced public adjuster. The initial call is free, with no obligation to hire us.
What's Different About a Fire Damage Claim?
Fire losses are rarely as simple as "the house burned down or it didn't." Even properties that survived a nearby fire often carry damage that isn't visible during a quick walkthrough, and insurance companies frequently under-scope these claims. A thorough fire damage claim should account for:
Structural and Total Loss Damage
Complete or near-complete destruction of a home or building, including foundation, framing, and load-bearing elements that may need full replacement even if some structure remains standing.
Smoke and Soot Contamination
Smoke particles travel far beyond the immediate burn area, settling into HVAC systems, insulation, drywall, and porous materials throughout a property. Smoke damage often requires specialized testing and remediation that insurers routinely underpay or reclassify to reduce their exposure.
Ash and Debris Contamination
Wildfire ash can carry heavy metals and toxic residue that require professional testing and removal, not just standard cleanup, particularly for properties near burned vegetation, vehicles, or structures.
Personal Property and Contents Loss
Furniture, electronics, clothing, and personal belongings lost or damaged in the fire, which require detailed inventory and documentation to be fully reimbursed.
Additional Living Expenses (ALE)
The cost of temporary housing, meals, and other expenses while your home is uninhabitable. ALE coverage is frequently underestimated by insurers relative to actual Los Angeles rental and relocation costs.
Ordinance or Law Coverage
Many older Los Angeles properties don't meet current building codes. If your policy includes ordinance or law coverage, you may be entitled to additional funds to bring a rebuild up to code, coverage insurers don't always volunteer or calculate correctly.
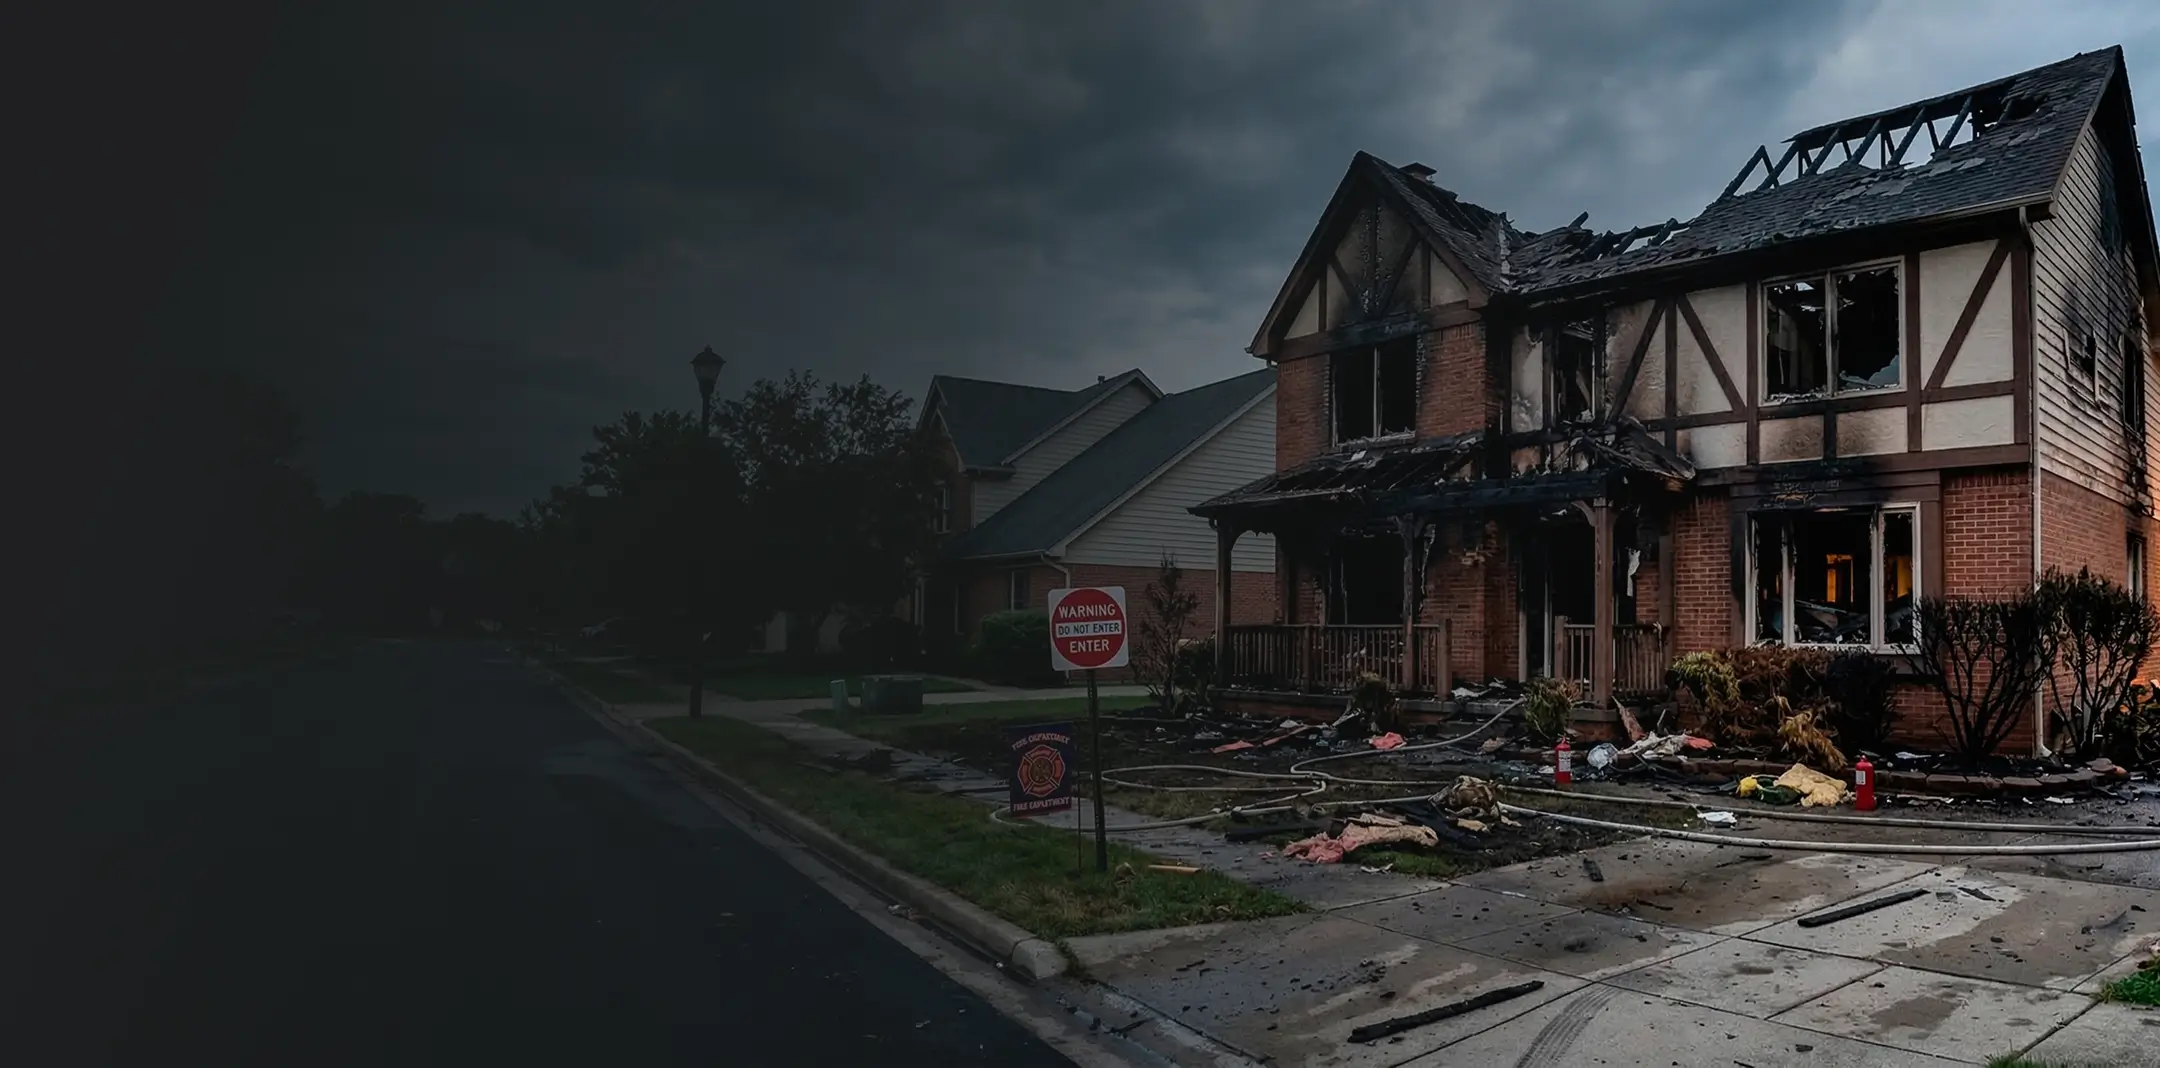
The Underinsurance Problem Facing LA Fire Survivors
Underinsurance has become one of the most serious issues facing Los Angeles fire victims. Survivors of the region's most destructive fires have widely reported that their coverage limits fell far short of what it actually costs to rebuild, leaving them to cover the shortfall out of pocket. State regulators have also opened investigations into how some major carriers handled fire claims, citing concerns about slow claim investigations and underpayment.
If you're worried your policy limits won't cover the true cost of rebuilding, or if you've already received an offer that seems disconnected from real construction costs, a public adjuster can help you understand what additional coverage, such as extended replacement cost or law and ordinance provisions, may still be available to you.

Fire Damage Claims We Handle in Los Angeles
- Wildfire and wildland-urban interface fire damage: losses from brush and wildfire events affecting hillside, canyon, and foothill-adjacent properties
- Structure fires: electrical fires, cooking fires, and other fires originating within a home or business
- Smoke and soot damage claims: contamination from nearby fires even when a structure itself didn't burn
- Total loss claims: full property destruction requiring complete rebuild
- Partial loss and remediation claims: properties that are salvageable but require extensive repair and decontamination
- FAIR Plan claims: claims filed under California's FAIR Plan for property owners who could not obtain standard fire coverage
- Business interruption and commercial fire claims: lost income and operating losses for Los Angeles business owners affected by fire
Frequently Asked Fire Damage Claim Questions
My home didn't burn down, but there's smoke damage. Is that covered?
In most cases, yes. Smoke and soot damage from a nearby fire is typically a covered peril under standard homeowners and commercial policies, even when the structure itself wasn't directly burned. Insurers sometimes underestimate the scope of smoke contamination, which is one of the most common reasons these claims come in underpaid.
What if my payout won't be enough to rebuild?
This is one of the most common concerns among Los Angeles fire claimants. If your dwelling coverage limit falls short of actual rebuilding costs, a public adjuster can review your policy for extended replacement cost provisions, ordinance or law coverage, and other add-ons that may close the gap, and can also challenge a scope of loss that undervalues the true cost to rebuild.
Do I need to hire a contractor before filing a fire damage claim?
No. You should document the damage and file your claim first. A public adjuster can help you build an accurate, defensible scope of loss before any repair or rebuild work begins, which protects you from underestimating what you're owed.
How is a fire damage claim different from a water or wind damage claim?
Fire claims often involve multiple layers of loss, structural damage, smoke and soot contamination, ash-related toxicity, contents loss, and additional living expenses, that all require separate documentation. Fire claims also tend to involve higher dollar amounts and more complex negotiations, especially after large-scale wildfire events affecting many policyholders at once.
How does Avner Gat, Inc. charge for its services?
Avner Gat, Inc. handles claims on a contingency basis, with our fee calculated as a percentage of the settlement.
Steps to Take After a Fire Damage Loss
Prioritize safety first
Only return to or enter a fire-damaged property once local authorities have confirmed it's safe to do so.
Document everything before cleanup begins
Photos and video of the damage, inside and out, are critical evidence for your claim.
Avoid signing any settlement offer before it's reviewed
Settlements are ongoing rather than a single check, and additional receipts can be submitted as the claim progresses, but an accepted offer is much harder to revisit.
Keep records of all fire-related expenses
Hotel stays, meals, and other costs may be reimbursable under your additional living expenses coverage.
Contact a public adjuster before extensive negotiations with your carrier
Early involvement typically leads to stronger, more complete claims.


