

Pasadena Fire Damage Claims Adjuster | Avner Gat, Inc.
When fire damages your Pasadena home or business, the number your insurance company offers first is rarely the number you're actually owed. Avner Gat, Inc. is a licensed public adjuster who helps Pasadena fire victims recover the full value of their claim, covering structural repairs, smoke and soot contamination, damaged belongings, and the cost of living elsewhere while your property is rebuilt.
We represent policyholders only. We're never paid by, or affiliated with, any insurance carrier. Our sole focus is advocating for the settlement your policy provides.


Why Pasadena Fire Victims Shouldn't Face Their Insurer Alone
As soon as you report a fire loss, your insurance company sends out its own adjuster to evaluate the damage. That adjuster works for the carrier, and their job is to manage the company's payout, not to make sure you're fully compensated. This imbalance is especially costly after a fire near Pasadena's foothill communities, where claims can involve everything from smoke infiltration to full structural loss.
Avner Gat, Inc. corrects that imbalance. Our public adjusters build your claim around the actual cost of rebuilding and replacing your property rather than an insurer’s reduced estimate. We also manage every conversation with your insurer, so you can focus on your family and your property instead of a drawn-out fight over your payout.
Why Pasadena's Foothill Location and Historic Homes Raise Fire Risk
Pasadena sits directly against the San Gabriel Mountains, placing many of its neighborhoods within the wildland-urban interface, areas where homes back up against brush, canyons, and dry hillside vegetation. During periods of drought and strong Santa Ana winds, these foothill-adjacent communities face a meaningfully higher risk of wildfire exposure than flatland neighborhoods elsewhere in the region.
Pasadena's architectural character adds a separate layer of risk. The city's abundance of century-old Craftsman bungalows and wood-frame homes means many properties were built with materials and layouts that are more vulnerable to fire spread than modern construction, and often still carry original electrical systems that increase the risk of an internal structure fire.
Together, these factors mean Pasadena property owners face fire exposure from two directions at once: wildfire encroaching from the foothills, and aging home systems that raise the risk of a fire starting inside the structure itself.
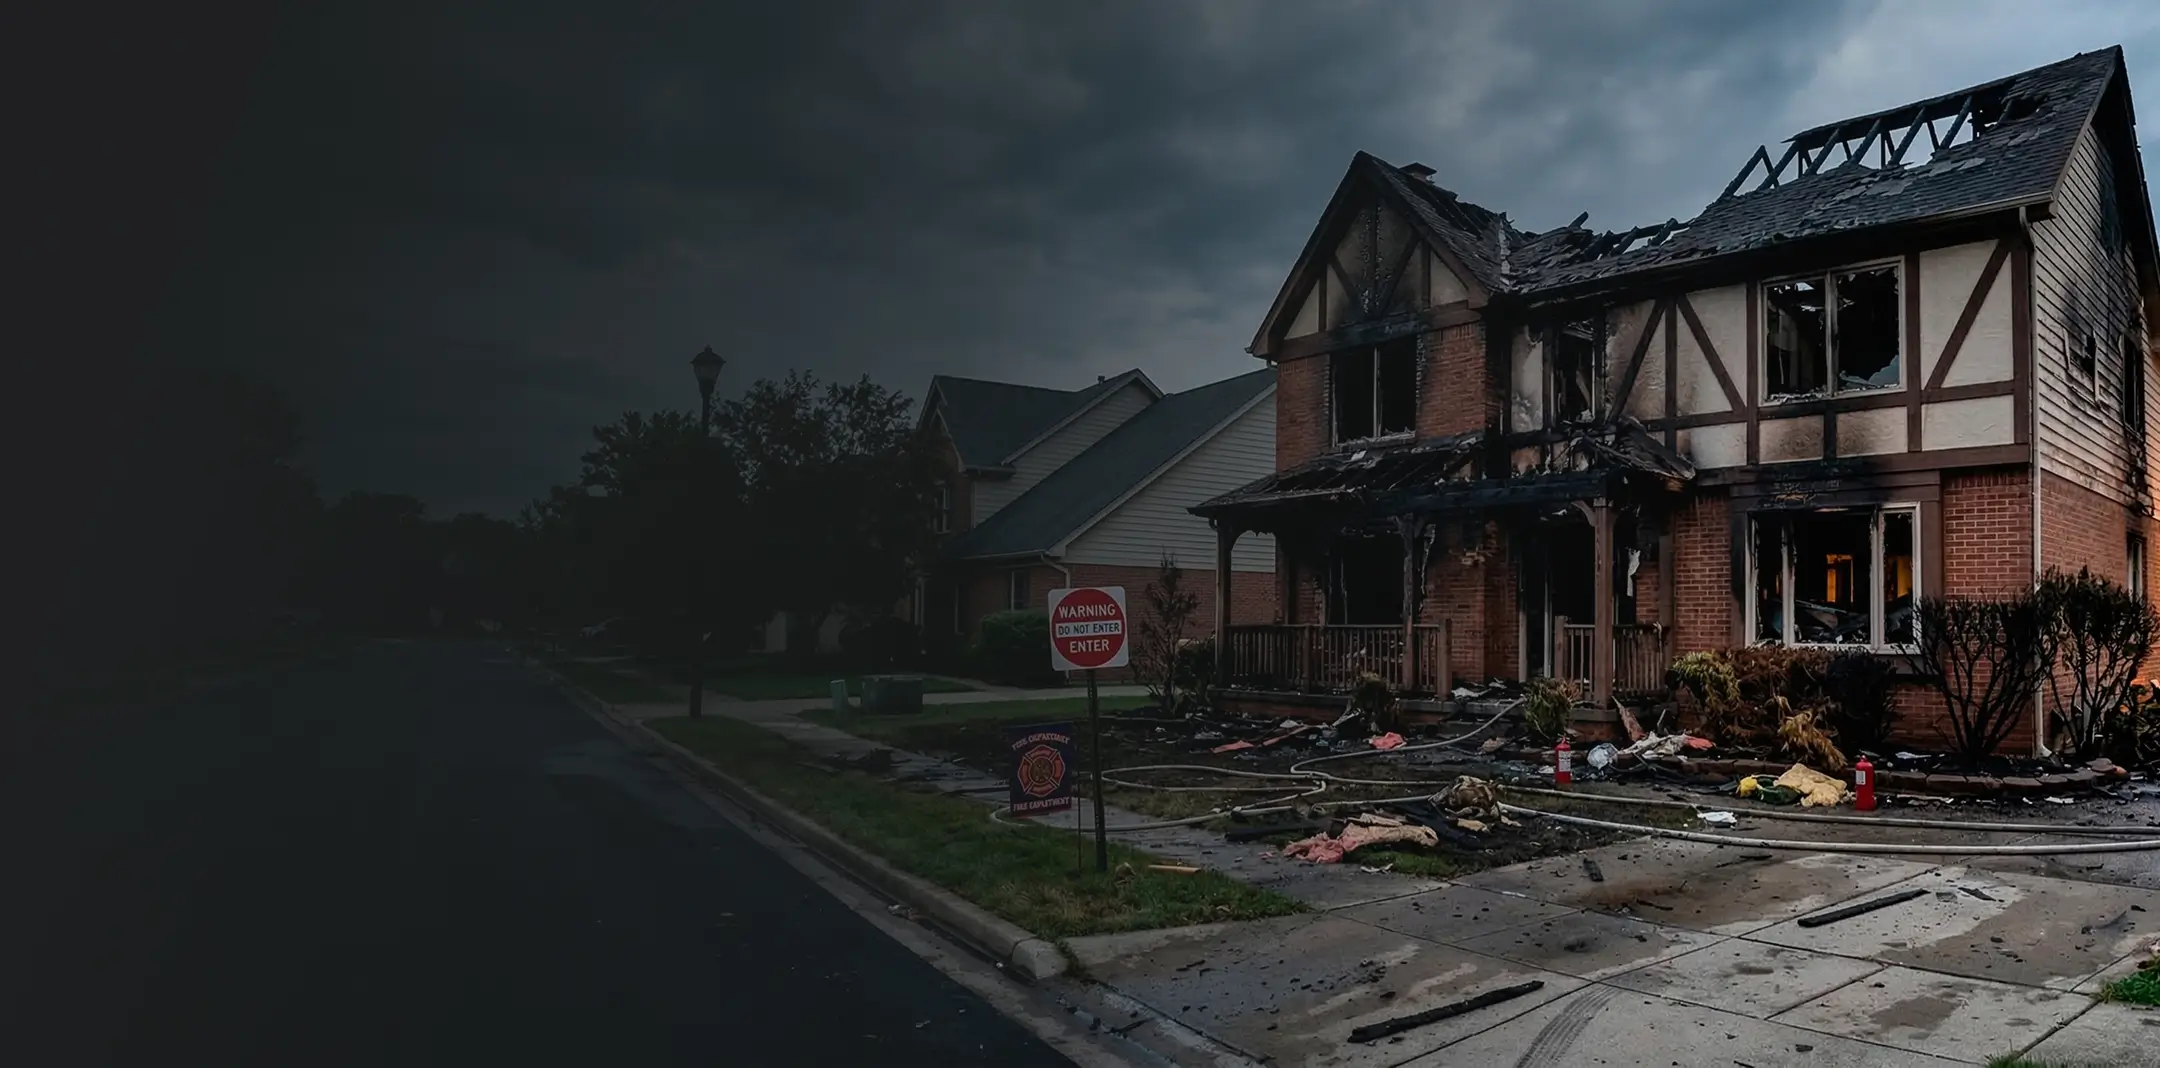

Underinsurance Is a Growing Concern for Pasadena-Area Fire Claims
Homeowners near Pasadena's foothill and canyon neighborhoods have increasingly found that their policy limits don't match what it actually costs to rebuild after a major fire. Rebuilding an older or historic home often costs more than a standard policy accounts for, particularly when custom materials, architectural detailing, or code-driven upgrades are involved.
If you're concerned that your coverage won't stretch far enough to rebuild, or you've already received a settlement offer that feels disconnected from real construction costs, a public adjuster can review your policy for extended replacement cost provisions, ordinance or law coverage, and other protections that may close the gap between your payout and your actual rebuilding costs.
Schedule a Fire Damage Claim Consultation
If a fire has affected your Pasadena home or business, don't navigate the claims process alone or settle for the first number your insurance company offers. The first call with Avner Gat, Inc. is free and there’s no obligation. We’ll talk through your policy and where your claim stands to help you understand exactly what you're entitled to recover.
Why Fire Claims Are More Involved Than Most Homeowners Expect
A fire claim is rarely as straightforward as "the property burned or it didn't." Even homes that weren't directly touched by flames often carry damage that isn't obvious during a first walkthrough, and insurers routinely under-scope these losses as a result. A properly built fire damage claim should account for:
Structural and Foundation Damage
Damage to framing, roofing, and load-bearing elements, which can require extensive rebuilding even when portions of the structure remain standing, a common scenario in Pasadena's older, wood-frame Craftsman and bungalow homes.
Smoke and Soot Infiltration
Smoke travels far beyond the visible burn area, settling into HVAC systems, attic insulation, and porous building materials throughout a property. This type of damage often requires specialized testing, and it's one of the most frequently underpaid components of a fire claim.
Wildfire Ash and Toxic Residue
Properties near burned hillsides, canyons, or wildland vegetation can face ash contamination carrying heavy metals and toxic byproducts, requiring professional testing and remediation rather than standard cleanup.
Contents and Personal Property Loss
Furniture, electronics, and personal belongings damaged or destroyed in the fire, which require careful documentation to be reimbursed at true replacement value rather than a reduced estimate.
Additional Living Expenses (ALE)
Coverage for temporary housing, meals, and related costs while your home is uninhabitable. These allowances are frequently underestimated relative to actual Pasadena-area housing and relocation costs.
Ordinance or Law Coverage for Historic and Older Homes
Many Pasadena properties, particularly its Craftsman and early-1900s homes, don't meet current building codes. If your policy includes ordinance or law coverage, you may be entitled to additional funds to rebuild to code, coverage insurers rarely calculate correctly or offer proactively.
Fire Damage Claims We Handle in Pasadena
- Wildfire and wildland-urban interface fire damage: losses affecting foothill, canyon, and hillside-adjacent properties near the San Gabriel Mountains
- Structure fires in older homes: electrical and structural fires linked to original or outdated wiring in Pasadena's historic housing stock
- Smoke and soot damage claims: contamination from a nearby fire even when the structure itself wasn't directly burned
- Total loss claims: full property destruction requiring a complete rebuild
- Partial loss and remediation claims: properties that are salvageable but require extensive repair and decontamination
- Historic home rebuild claims: claims involving ordinance or law coverage and code-compliant reconstruction of older properties
- Business interruption and commercial fire claims: lost income and operating losses for Pasadena business owners affected by fire
Frequently Asked Fire Damage Claim Questions
My home is near the foothills but wasn't directly burned. Can I still file a smoke damage claim?
In most cases, yes. Smoke and soot damage from a nearby wildfire is typically a covered peril under standard homeowners policies, even if the structure itself wasn't touched by flames. These claims are commonly underpaid because the full scope of smoke infiltration isn't always visible right away.
What if my settlement won't cover the cost to rebuild my historic home?
This is a frequent concern in Pasadena, where older homes often cost more to rebuild to code than a standard policy anticipates. A public adjuster can review your policy for extended replacement cost provisions and ordinance or law coverage, and can challenge a scope of loss that undervalues the true cost of restoring a historic property.
Should I get contractor bids before I file my claim?
Document the damage and file your claim first. A public adjuster can help build an accurate, defensible scope of loss before repair or rebuild work begins, protecting you from underestimating what you're actually owed.
How is a wildfire claim different from a structure fire claim?
Wildfire claims near the foothills often involve ash contamination, smoke infiltration across multiple properties, and area-wide contractor and material shortages that drive up rebuilding costs. Structure fires originating inside a home tend to involve more concentrated damage but can still carry significant smoke and water damage from firefighting efforts throughout the property.
How does Avner Gat, Inc. charge for its services?
Avner Gat, Inc. works on a contingency basis. Our fee is a percentage of the settlement, as agreed upon in our contract.
Can I hire a public adjuster after I've already started my claim?
Yes. You can bring in a public adjuster at any stage, whether you haven't filed yet, you're mid-claim, or you've already received an offer you believe is too low.
Steps to Take After a Fire Damage Loss
Wait for an official all-clear before returning
Only re-enter a fire-damaged property once local authorities confirm it's safe, particularly in foothill areas affected by wildfire.
Document everything before cleanup begins
Photos and video, inside and out, are essential evidence for your claim.
Don't sign a settlement before it's reviewed
Settlements are ongoing rather than a single check, and additional receipts can be submitted as the claim progresses, but an accepted offer is much harder to revisit.
Keep records of every fire-related expense
Hotel stays, meals, and other costs may be reimbursable under your additional living expenses coverage.
Involve a public adjuster early
Getting help before extensive negotiations begin typically leads to a stronger, more complete claim.


